
WILLAMETTE VALLEY VINEYARDS (WVVI) UPDATE: Raining on the Parade of Deception
Willamette Valley Vineyards is celebrating expansion. We see warning signs. An unpermitted hospitality vision, vineyard expansion into an industry glut, and preferred shares offered above market reinforce our view that WVVI’s growth story is increasingly disconnected from financial reality.
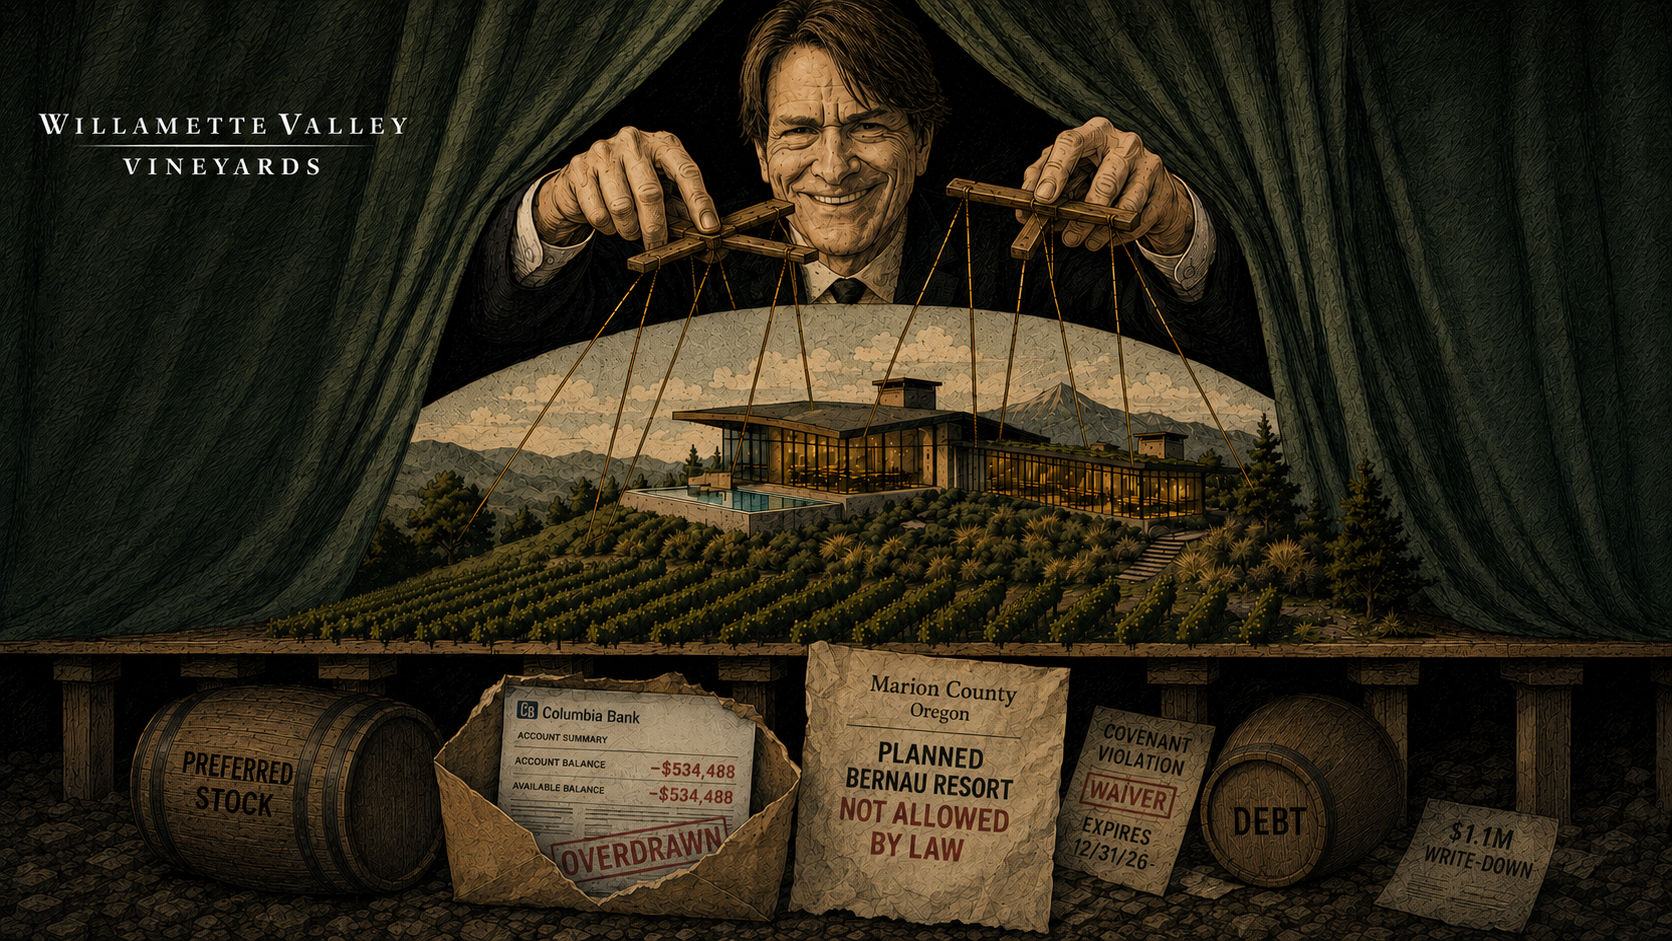
WILLAMETTE VALLEY VINEYARDS (WVVI): The Man Behind the Curtain
Willamette Valley Vineyards is running out of room to maneuver. Our latest report examines WVVI’s mounting liquidity crisis, growing preferred-stock burden, RNDC-related losses, and a proposed destination resort that is not allowed under Oregon law. We explain why management’s narrative does not match the financial reality and why we believe the common equity could ultimately be worth little to nothing.
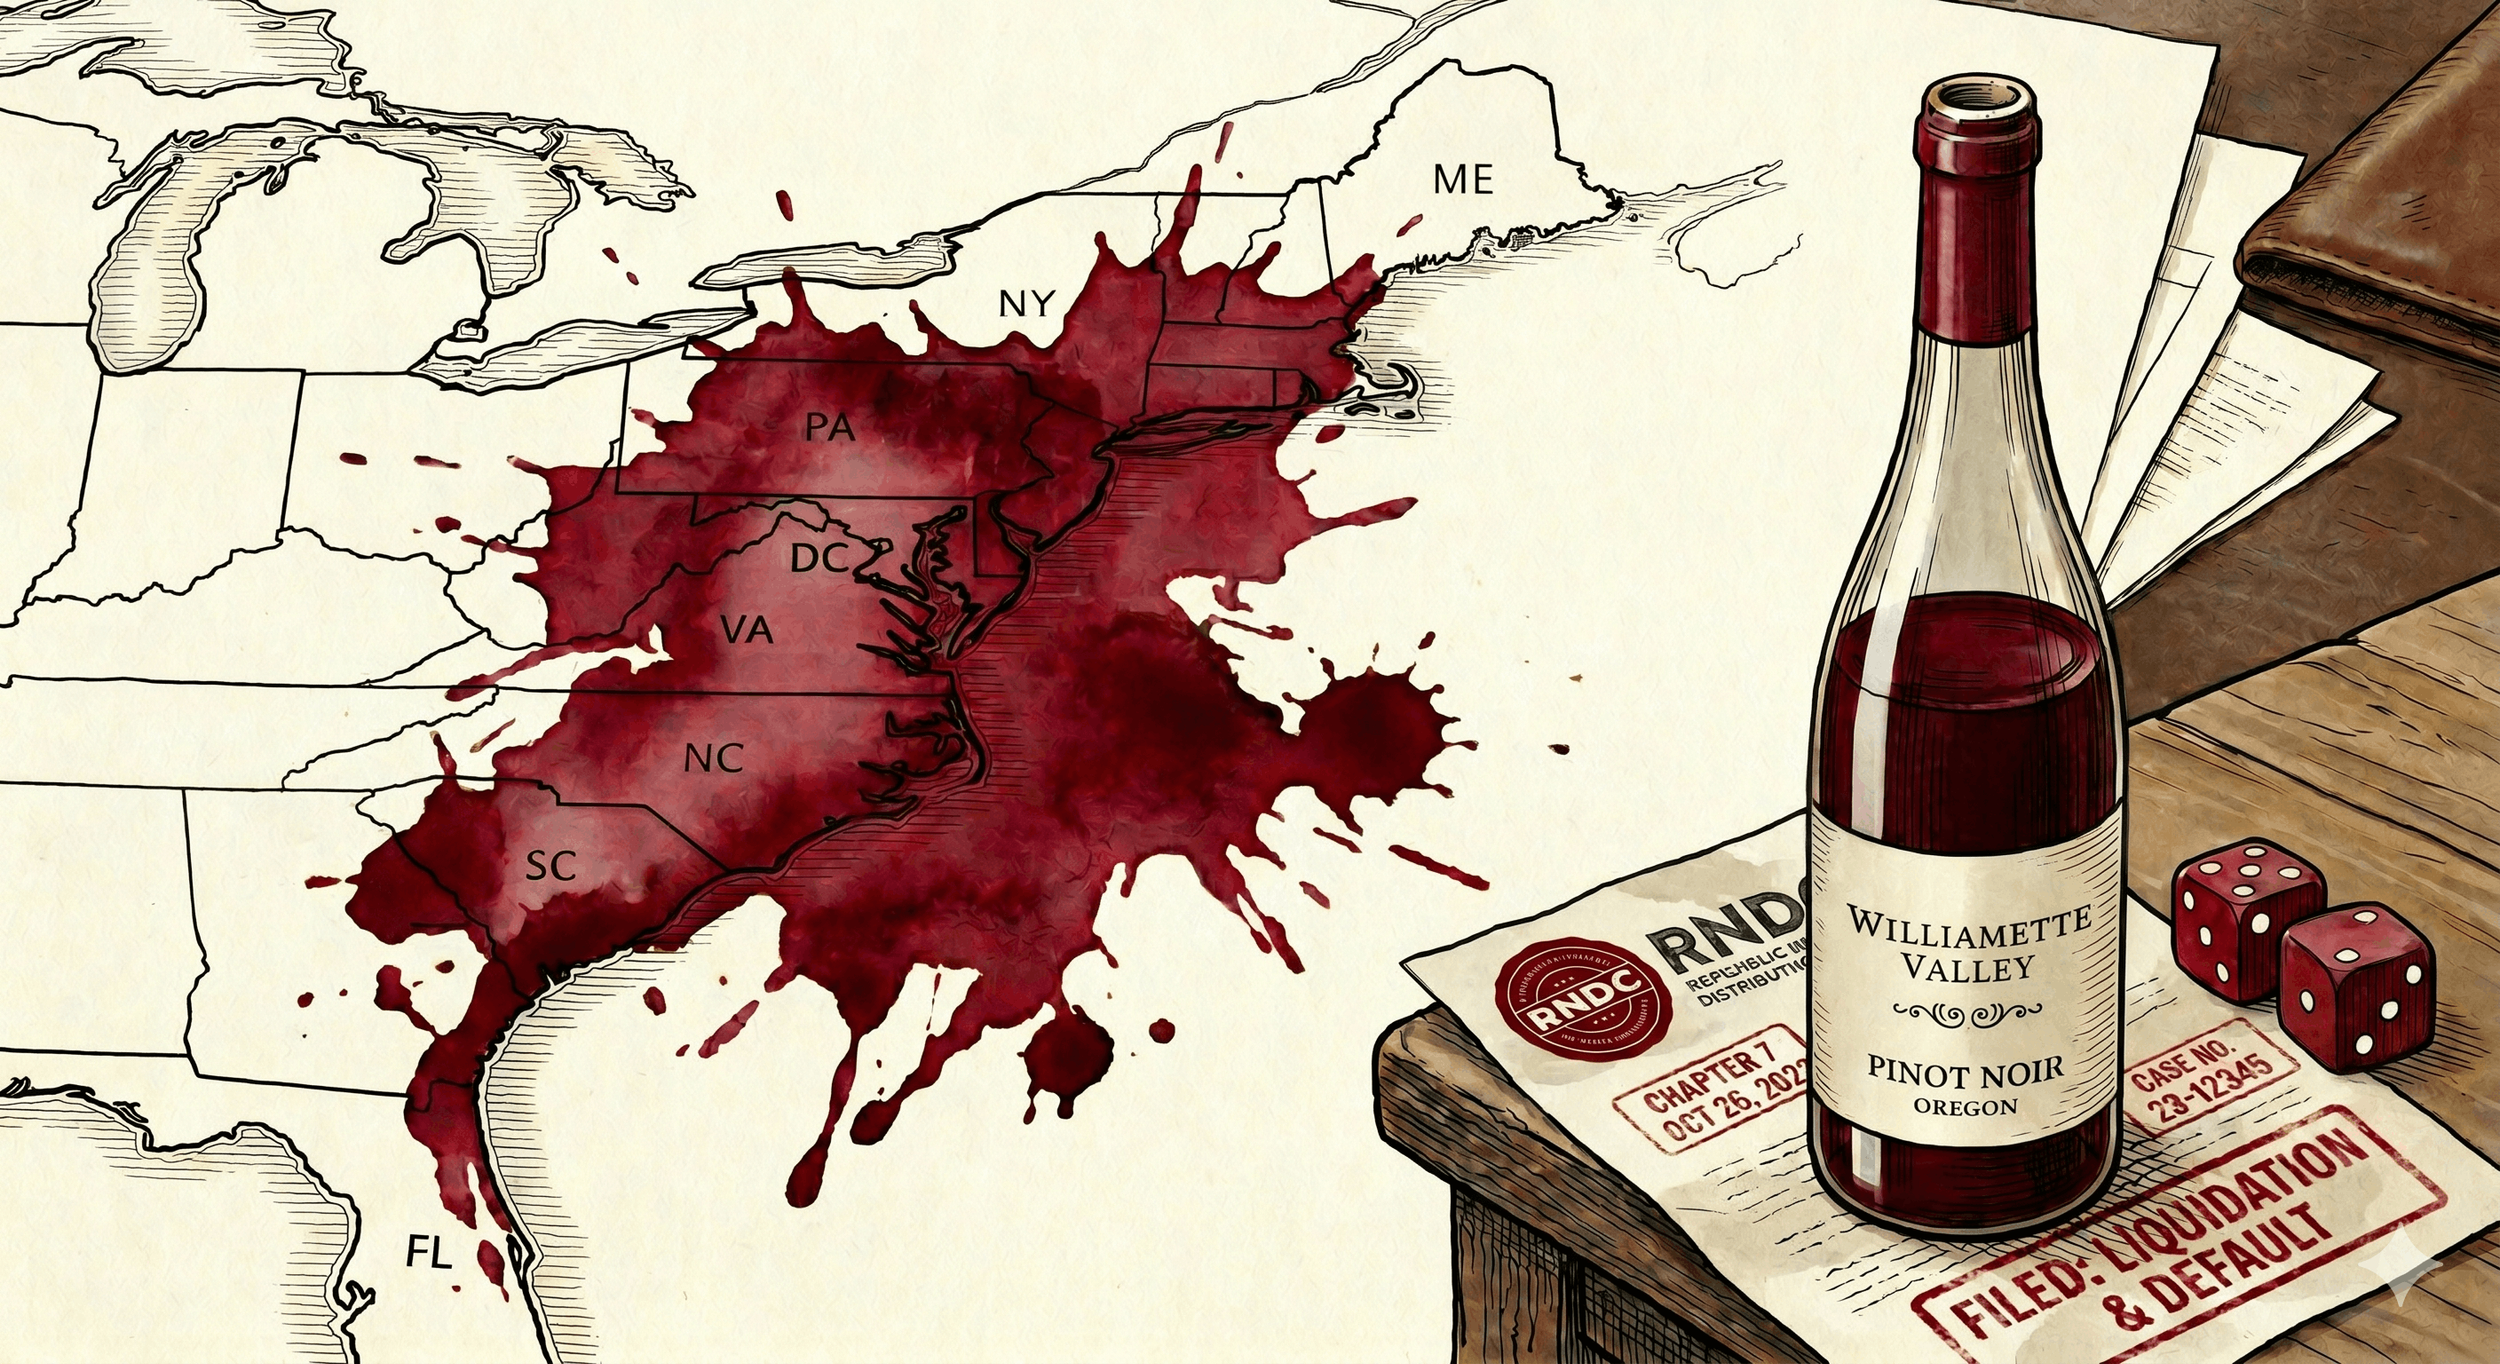
WILLAMETTE VALLEY VINEYARDS (WVVI): SOUR GRAPES, STRESSED DISTRIBUTOR
Willamette Valley Vineyards’ latest East Coast distribution reshuffle was presented as a growth initiative, but distributor RNDC’s ongoing collapse makes WVVI look materially riskier than management’s recent press releases suggest. The company aligned distribution in New York and parts of the Mid-Atlantic with Republic National Distributing Company in February 2026 even though RNDC had already shown signs of stress in key markets, making the decision look less like opportunistic expansion and more like a gamble with counterparty risk.

WILLAMETTE VALLEY VINEYARDS (WVVI): Not-So-Great Value
As an Oregon-based hedge fund, we often get the opportunity to more closely investigate local companies that are otherwise too small to register on most firms’ radars. Willamette Valley Vineyards (WVVI) is one of those companies. As one of the largest corporate vineyards in the state and a big player in a currently-ailing industry (the kids just don’t drink how they used to), it has shown up on our equity value screen programs more than a few times.
Unfortunately, just appearing in a value search does not make a value company. It is as much our job as managers to identify value traps as it is to pick out the potential true bargains. The low valuation of current trading seems to be justified. Let’s dig into why.